Free template
Free Sales Receipt Template (PDF, Word & Excel)
A sales receipt records goods or services paid for at the time of sale. The sample in this sales receipt template records the items sold and the payment received for that sale. It identifies the seller and buyer where needed, itemizes what was sold, shows the amount and payment method, and can state the return policy that applied at checkout. It is not a promise that every return is allowed and it is not automatically a tax invoice. Download the blank PDF, Word or Excel template and adapt only the fields that match the sale.
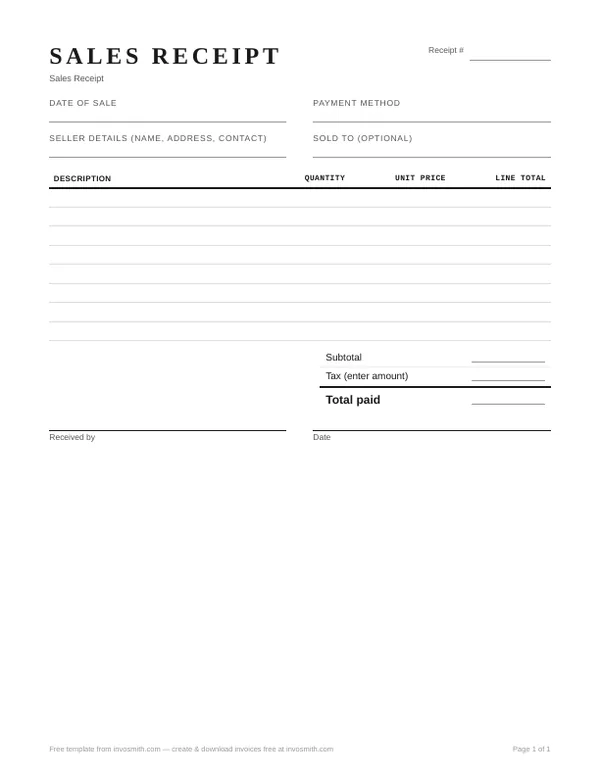
Download the sales receipt template
Sales receipt template
An itemized receipt for goods sold and paid for on the spot.
Every download is free — no email, no sign-up, no watermark.
The Word file also opens in Google Docs. In the Excel file the line totals and subtotal are live formulas; the tax figure is a cell you type in yourself.
What goes on a sales receipt
A sales receipt is an invoice's shape with a receipt's meaning: the same item grid, but everything on it already happened. The fields:
- Receipt number — one sequence, in order, separate from any invoice numbering you use. Two documents with the same number is the outcome to avoid.
- Date of sale — the sale and the payment happened together; one date covers both.
- Seller details — business name, contact, and where returns or questions should go. On a receipt handed to a stranger at a market stall, the contact line is the difference between a customer and a chargeback.
- Sold to — optional for a walk-up cash sale, worth filling for anything with a warranty, a serial number, or a delivery to arrange.
- Line items: description, quantity, unit price, line total — specific enough to identify what left: "Bookshelf, oak, 5-shelf" rather than "furniture". For serialized goods, put the serial number in the line.
- Subtotal, tax and total — the Excel file calculates line amounts, subtotal and total; PDF and Word amounts are entered manually. The tax cell is manual in every format. Enter only the amount that applies and check the final total.
- Payment method — cash, card, or transfer reference, next to the total it settled.
- Received by — whoever took the payment signs or initials. It's still a receipt: somebody received the money, and the paper should say who.
Sales receipt sample for goods paid on the spot
Here is a completed sales receipt from a small maker's stall — three line items and a total before any applicable tax:
| Field | Entry |
|---|---|
| Receipt no. | 0517 |
| Date of sale | August 2, 2026 |
| Sold to | Walk-in customer |
| Item 1 | Soy candle, 8 oz — 3 × $14.00 = $42.00 |
| Item 2 | Gift box, kraft — 1 × $18.00 = $18.00 |
| Subtotal | $60.00 |
| Tax (if applicable) | — |
| Total before applicable tax | $60.00 |
| Payment method | Card |
| Received by | J. Whela (signature) |
The line items are doing the real work. "3 × $14.00" means that if one candle comes back cracked next week, everyone can see what one candle cost. A receipt that just says "Goods" turns a line-item refund into a negotiation. Enter any applicable tax separately; the receipt records the amount you enter.
When something comes back
Create a separate refund record that cites the original receipt number, item and amount. Do not assume the refund is exactly the pre-tax line price: enter any tax adjustment supplied by the seller’s applicable system or adviser. Keep the original sale and later refund as separate dated records.
If you're the buyer keeping the receipt
An itemized receipt helps identify what was bought. A card slip, bank record, order confirmation, warranty record or other proof may also support the transaction. Check the item lines before leaving and keep the records for the period relevant to returns, warranties, tax and disputes.
Add a return-policy field without overstating it
Write the policy the customer actually saw at the time of sale — for example, “Returns accepted within 14 days with this receipt; opened custom items excluded.” Do not use the template to remove statutory consumer rights or promise rights the seller does not offer.
| Receipt field | Example |
|---|---|
| Items | 2 cotton shirts; 1 belt |
| Subtotal | $78.00 |
| Tax (if applicable) | — |
| Total paid before applicable tax | $78.00 |
| Payment method | Card ending 1842 |
| Return policy | Returns within 14 days with receipt; statutory rights are not limited |
Consumer receipt checks by country
The receipt records the transaction; consumer and tax rules sit around it. Use the official source for the country of sale.
United States
Receipt requirements and return policies vary by state and sale type. State the actual policy, preserve the itemized transaction record and avoid implying that an “all sales final” line overrides rights that cannot be waived.
California
California consumer guidance explains the state refund-policy disclosure rule and exceptions. Use the current official wording before publishing a store-specific final-sale policy.
United Kingdom
GOV.UK guidance distinguishes faulty goods from change-of-mind returns. A shop policy can add convenience but cannot remove statutory rights.
Australia
ACCC proof-of-purchase guidance covers transaction records, while the Australian Consumer Law controls remedies. A sales receipt and a tax invoice are not automatically the same document.
New Zealand
The archived New Zealand source in this release covers services, not a general merchandise-return policy. This page therefore makes no specific goods-return-window claim for New Zealand. Check current official goods guidance before publishing one.