Free template
Free Donation Receipt Template (PDF, Word & Excel)
A donation receipt records a gift after an organization receives it. The useful version identifies the organization and donor, dates and describes the gift, and says whether the donor received goods or services in return. The blank PDF, Word and Excel downloads below are editable starting points, not automatic proof that a gift is tax-deductible. Choose the wording for the country and organization issuing the receipt, and do not reuse a U.S. rule as a universal format.
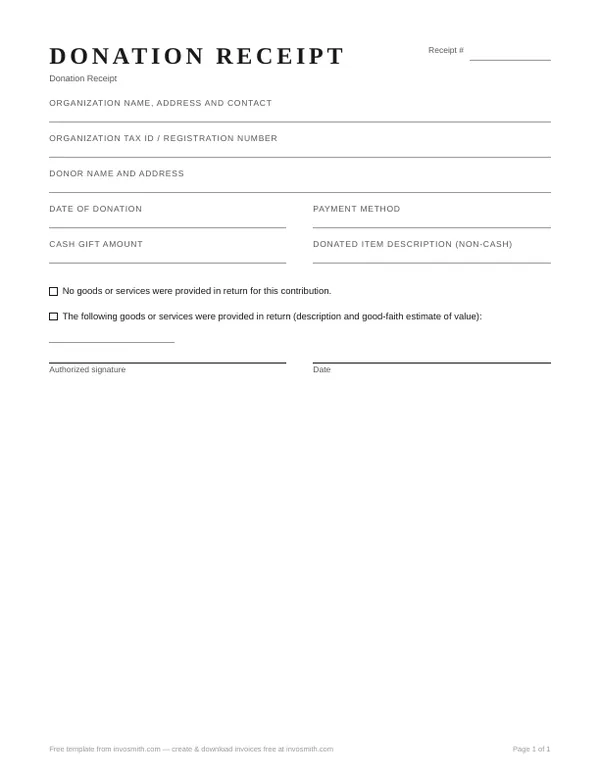
Download the donation receipt template
Donation receipt template
A receipt for cash or donated goods, with an editable in-return statement.
Annual donation summary
A twelve-entry yearly contribution log with a cash total and benefit-in-return field.
Every download is free — no email, no sign-up, no watermark.
The Word file also opens in Google Docs.
What goes on a donation receipt
A donation receipt has a different center of gravity from a payment receipt: the organization's details carry the document, and one unusual line — what the donor received in return — does work no other receipt does.
- Organization name, address and contact — the receipt is issued on the organization's paper, so its details lead the page, not the donor's.
- Organization tax ID / registration number — include the identifier only when the issuing country or organization requires it. Required fields differ: do not treat a U.S. EIN, Canadian registration number or another country’s identifier as interchangeable.
- Receipt number — one sequence for all donation receipts. Organizations that issue hundreds a year live and die by this field at reconciliation time.
- Donor's name and address — as the donor wants it recorded.
- Date of the donation — record the date using the rule that applies to the gift and jurisdiction. In the U.S., IRS Publication 526 says a mailed check is treated as delivered on the date it is mailed; do not replace that with a blanket “date received” rule.
- For a cash gift: the amount — figures on the line, and the payment method next to it.
- For a donated item — describe what the organization received and its condition. Do not assume every country uses the same value rule: U.S. acknowledgments generally describe non-cash gifts without stating value, while a Canadian official donation receipt includes the fair market value and eligible amount. Use the country panel below before completing this field.
- What the donor received in return — state whether the organization provided goods or services for the gift. If it did, describe them and use the valuation or disclosure rule that applies where the receipt is issued. The template supplies editable “nothing provided” and “something provided” choices; neither choice by itself establishes deductibility.
- Authorized name or signature — identify the person or role responsible for the record when your workflow or applicable rules call for it. Do not assume every country makes a handwritten signature mandatory.
A filled-in donation receipt, line by line
This fictional cash-gift example shows the organization, donor, date, amount and benefit-in-return statement. It is an example of the fields, not a determination that the gift is deductible.
| Field | Entry |
|---|---|
| Organization | Riverbend Community Pantry |
| Tax ID | 00-0000000 (your organization's real EIN) |
| Receipt no. | 2026-118 |
| Donor | Alma Reyes |
| Date of donation | August 2, 2026 |
| Amount | $250.00 |
| In-return statement | No goods or services were provided in exchange for this donation. |
| Authorized signature | D. Osei, Treasurer |
For a U.S. donor claiming a deduction, IRS Publication 1771 says a single contribution of $250 or more needs a contemporaneous written acknowledgment. The acknowledgment must state whether goods or services were provided; it does not prescribe one magic sentence. Other countries use different official-receipt fields, so apply the country panel below.
If you're the donor collecting receipts
Ask for the receipt while the gift is still easy to trace. Check the organization, gift date, cash amount or property description, and any benefit received in return. Then compare the record with the issuing country’s requirements: tax identifiers, valuation fields, signatures and declaration wording are not universal.
Three donation receipt examples
The same blank template can document three different gift patterns. The entries below show what changes; they are examples, not determinations that a donor can claim a deduction.
| Gift | Receipt entry | What to check |
|---|---|---|
| Cash gift | $300 received by bank transfer; no goods or services provided in return | Organization identity, gift date, amount and country-specific acknowledgment wording |
| In-kind gift | Twelve folding chairs, used, good condition | Describe the property. Apply the issuing country’s rules before including any value. |
| Dinner or other benefit | $150 received; donor received a dinner valued at $60 | Describe the benefit and its value where the applicable rules require it. |
Donation receipt rules by country
Start with the short summary, then open only the country that applies. These are field checks from official sources, not a promise of deductibility or charity status.
| Country | Use this template as | Key check |
|---|---|---|
| United States | Written acknowledgment | Single contributions of $250 or more need contemporaneous written acknowledgment for a deduction |
| Canada | Official donation receipt draft | CRA-prescribed fields and eligible-amount rules apply |
| Australia | DGR receipt draft | Check that the recipient is entitled to issue a deductible-gift receipt |
| United Kingdom | Donation record | Gift Aid declarations are a separate record |
United States — written acknowledgment
IRS Publication 1771 says a donor claiming a deduction for a single contribution of $250 or more must obtain a contemporaneous written acknowledgment. It may be paper or electronic and an annual summary may acknowledge multiple gifts. The acknowledgment identifies the organization, states cash amount or describes non-cash property, and states whether goods or services were provided in return.
Separate gifts below $250 are not combined merely because the annual total exceeds $250. Do not reuse old token-benefit dollar thresholds: Publication 1771 labels them inflation-adjusted.
Canada — official donation receipts
CRA guidance lists mandatory information for official donation receipts. For a non-cash gift, the receipt includes the fair market value and eligible amount, so the U.S. “description only, no value” approach is not universal.
Australia — DGR receipts
ATO guidance explains the information a deductible gift recipient should show on a receipt. Confirm the recipient’s DGR status and gift type before presenting the document as tax-deductible.
United Kingdom — Gift Aid is separate
HMRC Gift Aid guidance treats the donor declaration and the charity’s claim records as separate requirements. A general thank-you receipt does not replace those records.